法国国债遭历史性抛售 法德利差突破170基点French Bonds Face Historic Sell-Off as Spread Over Bunds Tops 170 Basis Points
法国国债市场本周遭遇历史性抛售压力,基准10年期国债收益率自2002年以来首次突破5%。截至周四,法国与德国10年期国债利差扩大至170个基点以上,法国主权信用违约互换(CDS)所衡量的违约保险成本也攀升至2010年代初欧债危机以来的最高区间。与利差扩大相对应的是,衡量法国债券风险的关键指标正接近有记录以来的最大单周涨幅。这一波市场剧烈震荡发生在法国财政基础与政治治理承受多重考验之际。法国政府已将2026年经济增长预期下调至0.5%,其债务与GDP之比在2026年第二季度末升至119%,在欧元区21国中保持着位居前列的赤字规模。国内持续的政治动荡与社会抗议削弱了投资者对当局推行财政稳定措施的预期,零售企业家乐福因抗议冲击预警全年业绩并承受20亿欧元市值蒸发。尽管欧洲现行制度防范机制相较以往更加健全且暂未出现即时流动性危机,但多国机构分析人士警告,随着法国在固定收益市场日益受到外围化审视,跨境借贷成本碎片化与跨市场溢出风险依然需要高度警惕。
France's sovereign bond market suffered historic turbulence this week as its benchmark 10-year yield rose above 5% for the first time since 2002, while the closely watched 10-year yield spread over German bunds widened past 170 basis points on Thursday to levels unseen since the euro zone sovereign debt crisis of the early 2010s. The cost of insuring French government obligations against default, tracked via credit default swaps, also climbed to its highest point since that era, with a key risk gauge nearing its largest weekly increase on record. The abrupt market repricing takes place as France faces mounting fiscal and governance challenges. The French government downgraded its 2026 economic growth forecast to 0.5%, following a second-quarter debt-to-GDP ratio of 119% and persistent deficits among the highest in the 21-nation euro area. Persistent political volatility and social unrest have compounded investor doubts regarding Paris's capacity to deliver planned fiscal stabilization measures, with supermarket operator Carrefour SA losing 2 billion euros in market value after cautioning over protest damage. While institutional strategists emphasize that upgraded regional frameworks reduce systemic liquidity threats compared to 2011, sovereign bond market participants caution that fragmentation and cross-border spillover risks remain active.

01法德国债利差突破170基点 风险指标创下纪录级别单周涨幅French-German Bond Spread Widens Past 170 Basis Points Amid Historic Sell-Off
在经历持续抛售之后,法国固定收益市场的基准借贷成本走高至多年未见的位置。法国10年期基准国债收益率在突破5%大关后继续大幅上行,刷新2002年以来的最高水平。与此同时,衡量主权压力的关键指标——法德10年期国债收益率利差在周四超过170个基点,重回2010年代初欧债危机爆发时的区间,彭博社报道称相关风险指标正趋近有记录以来的最大单周涨幅。
Benchmark borrowing costs across France's sovereign debt market escalated sharply following prolonged selling pressure, reaching levels not recorded in more than two decades. The yield on France's 10-year benchmark government bond surpassed the 5% threshold before climbing steeply, posting its highest level since 2002. At the same time, the yield spread between 10-year French bonds and German bunds—a primary metric tracking sovereign distress—widened beyond 170 basis points on Thursday, returning to levels seen during the euro zone sovereign debt crisis of the early 2010s, with Bloomberg reporting that a key risk gauge neared its largest weekly increase on record.
除现券市场的利差走阔外,以信用违约互换(CDS)为代表的法国政府主权违约保险成本也升至欧债危机时期的最高点。外汇市场上,欧元自年初以来对美元累计跌幅接近5%。彭博社与CNBC报道说明,随着法国与德国的举债成本差距迅速扩大,固定收益投资者正在重估持有法国资产的风险溢价,而欧元区内部借贷成本发生碎片化偏离的可能性也重新成为多方机构关注的重点。
Beyond the cash bond market, the cost of insuring French government obligations against potential default through credit default swaps rose to its highest point since that sovereign debt crisis. Concurrently, foreign exchange trading reflected persistent strain, with the euro falling almost 5% against the U.S. dollar since the start of the year. Reporting from CNBC and Bloomberg indicates that fixed income investors are actively repricing risk premiums on French debt, as the expanding borrowing cost differential with Germany revives institutional concerns regarding debt repayment friction and financial fragmentation across the shared currency area.
02宏观基本面承压:债务与GDP比率达119% 增长预期遭下调Macroeconomic Fundamentals Weaken with 119% Debt-to-GDP Ratio and Growth Cuts
法国国债承受的抛售压力源于疲弱的宏观基本面和沉重的公共财政负担。法国政府已经将2026年经济增长预期下调至0.5%,反映出实体经济扩张趋于停滞。在增长放缓的同时,法国在2026年第二季度末的债务与GDP之比攀升至119%,其赤字规模在欧元区21国内部居于前列。玛泽咨询首席经济学家乔治·拉加里亚斯分析指出,法国当前119%的债务比重已接近希腊在2009年底债务危机初期达到的128%水平,法国事实上已经处于自身的主权债务压力之中。
The underlying pressure on French debt instruments stems directly from deteriorating public finances and a slowing economic expansion. The French government downgraded its 2026 economic growth forecast to just 0.5%, reflecting stagnant national output. At the same time, official data show France's debt-to-GDP ratio reached 119% at the end of the second quarter of 2026, leaving the country with one of the highest deficit-to-GDP ratios across the 21-nation euro area. George Lagarias, chief economist at Forvis Mazars, observed that France is already experiencing a debt crisis, pointing out that its 119% ratio sits uncomfortably close to the 128% recorded by Greece in late 2009 during the initial phase of the euro zone debt crisis.
财政指标的恶化与法国国内政治动荡以及社会抗议相互交织,削弱了投资者对巴黎当局执行公共财政稳定方案能力的信心。ING全球宏观研究主管兼欧元区首席经济学家卡斯滕·布热斯基表示,尽管法国政府并无发生即时流动性危机的风险,但债券市场信任度的流失与危机局势必须促使官方形成紧迫感。经济学家同时警告,不断升高的国债收益率与日益沉重的利息支出正在形成相互强化的借贷压力,进一步推高政府的总债务规模。
Worsening balance sheets have converged with domestic political volatility and social protests, compounding doubts over Paris's ability to implement planned fiscal consolidation measures. Carsten Brzeski, global head of macro research and chief euro zone economist at ING, stated that while the French administration faces no imminent liquidity failure, the pronounced lack of trust in sovereign bond markets and the continuing crisis should inject a strong sense of urgency into Paris. Economists further caution that rising borrowing yields and expanding interest outlays now threaten to create a compounding feedback loop, directly adding to the state's total debt burden.
法国主权债务与社会危机演进历程Timeline of France's Sovereign Debt and Social Unrest Crisis
梳理从紧缩预算出台、全国抗议蔓延到法国国债遭遇历史性抛售的发展过程。
Traces developments from the austerity budget and street protests to the historic sell-off in French government debt.
法国总理勒科尔尼公布2027年预算草案,寻求通过430亿欧元紧缩举措及冻结公共部门薪资,将财政赤字率从5.4%压降至5%。
French Prime Minister Sébastien Lecornu presented a draft 2027 budget seeking €43 billion in recovery measures and public wage freezes to lower the deficit to 5%.
抗议危旧校舍的高中生示威蔓延至巴黎和马赛等多地,造成数百所学校瘫痪,法国司法部通报逮捕5060人,其中87%为未成年人。
High school demonstrations over hazardous school buildings spread to cities including Paris and Marseille, resulting in 5,060 arrests, with 87% being minors.
学生、工会、农民与黄马甲群体联合发起示威抗议生活成本高企,全法游行人数近20万,巴黎警方在晨间行动中拘押逾60人。
French students, trade unions, farmers, and Yellow Vest activists rallied nationwide against high living costs, drawing nearly 200,000 demonstrators.
对法国财政整顿及政治动荡的担忧加剧,法国与德国10年期国债利差周四突破170个基点,触及欧债危机以来的最高水平。
Mounting doubts over France's fiscal consolidation pushed the 10-year yield spread over German bunds beyond 170 basis points on Thursday.
法国10年期国债收益率自2002年以来首次升破5%,债务占GDP比例达119%;零售巨头家乐福因骚乱冲击预警全年业绩,市值蒸发20亿欧元。
France's benchmark 10-year yield rose above 5% for the first time since 2002, while retailer Carrefour lost €2 billion in market value after issuing a protest-related warning.
03实体商业受波及:家乐福因抗议冲击预警全年业绩Corporate Sector Impact: Carrefour Issues Outlook Warning Following Protests
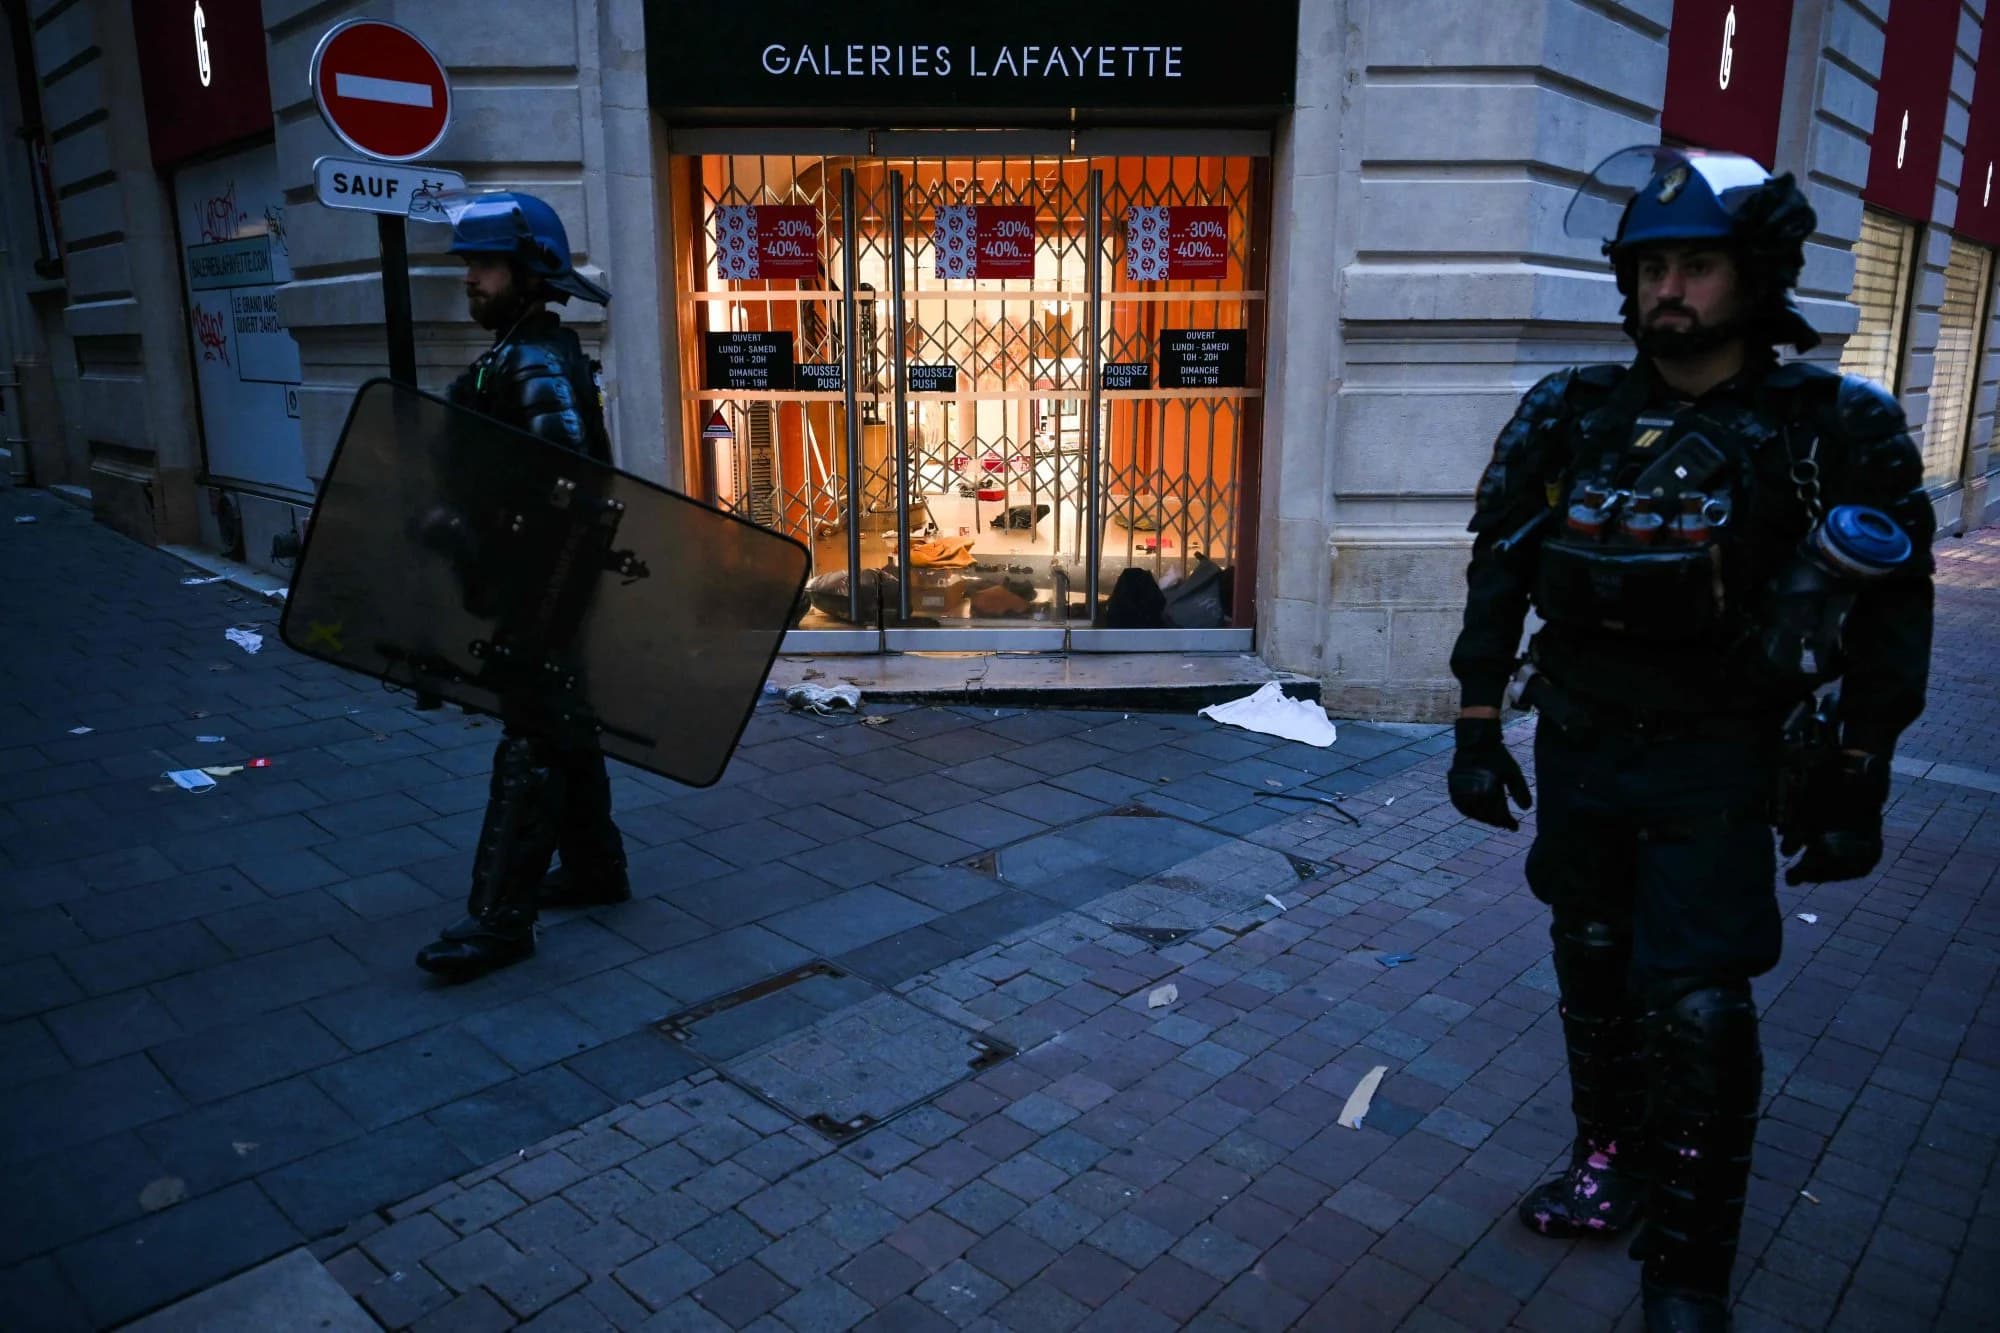
政治危机与社会抗议引发的动荡正由公共金融领域传导至法国的实体工商业。在抗议活动扩散期间,法国大型连锁超市运营商家乐福(Carrefour SA)公开发布警示,指出全法范围内的暴力抗议与抢劫事件将对集团的全年业绩前景造成沉重打击。受此业绩预警冲击,家乐福股票遭遇抛售,公司市值在短时间内蒸发约20亿欧元。
The fallout from widening social unrest and political turbulence is extending beyond sovereign debt markets into France's domestic corporate sector. Supermarket operator Carrefour SA cautioned investors that violent protests and looting across the country will weigh heavily on its full-year business outlook. The financial impact was immediate, with the retail giant experiencing a steep stock drop that erased approximately 2 billion euros in market value.
根据彭博社报道,家乐福股价走势显示其即将录得自全球金融危机以来表现最差的单周表现。法国零售巨头所面临的运营中断和损失,直接反映出持续的街头抗议与社会不稳定正在对私营部门的实际收入与投资者信心造成切实损害,令外界对法国宏观经济环境以及企业在混乱局势下的盈利前景产生更广泛的担忧。
Reporting from Bloomberg indicates that Carrefour's shares are positioned to log their worst weekly performance since the global financial crisis. The disruptions, property destruction, and reduced commercial activity encountered by one of the country's most prominent retailers underscore the direct operational costs that persistent street demonstrations impose on private industry, further undermining confidence in corporate earnings against a deteriorating macro backdrop.
04机构评估区域蔓延风险:机制虽有改善但非核心国家仍受审视Assessing Regional Spillover: Stronger Firewalls Yet Lingering Fragmentation Risks
针对法国国债抛售是否会引发系统性蔓延,接受CNBC采访的分析人士普遍认为,得益于过去十余年推行的制度改革,欧元区的传染风险整体保持在有限范围。Ninety One多元资产收益主管约翰·斯托普福德指出,法国在固定收益投资者眼中已从核心或半核心国家逐渐被视为外围国家,其利差可能需要达到200个基点左右才会被普遍判定为全面危机。他表示,法国利差虽已超越本国在2010年代初外围危机峰值时的水准,但仍远低于当年西班牙、意大利、希腊和爱尔兰的极端水平,市场倾向于认为形势可能需要进一步恶化才会促使欧盟机构介入干预。
Addressing whether French debt turbulence could trigger broader systemic contagion, market strategists surveyed by CNBC broadly agreed that structural reforms enacted over the past decade keep regional contagion risks contained, even as price action echoes the post-financial crisis era. John Stopford, head of multi-asset income at Ninety One, observed that fixed income investors increasingly treat France as a peripheral issuer rather than a core or semi-core European nation. Stopford noted that sovereign spreads would likely need to trade in the 200 basis point range before being widely treated as a full-blown crisis. He explained that while French spreads have surpassed their peak from the early 2010s peripheral crisis, they remain far below the extreme levels previously reached by Spain, Italy, Greece, and Ireland, leading investors to anticipate that conditions would need to worsen before European Union institutions step in to cap damage.
贝莱德策略团队指出,当前的宏观环境与2011年至2012年欧债危机时期存在实质性差异,欧元区应对金融压力的制度机制已显著健全,但跨境波动与溢出效应依然可能出现。该机构分析称,全球利率重置引发的资本争夺正重塑固定收益市场格局,政府借贷规模扩大与人工智能相关投资共同推升了整体融资成本,导致基本面恶化的主权借款方承受更严格的外部审视。斯托普福德补充表示,面对流动性极强且充满不确定性的局面,其投资团队目前已选择基本规避所有欧洲非核心国家的债务资产。
BlackRock strategists highlighted that the prevailing macroeconomic environment is materially different from the 2011-2012 euro zone sovereign debt crisis, noting that the currency bloc is structurally better prepared to absorb financial stress, though cross-border volatility and spillover effects remain active threats. The firm explained that French selling reflects how intense capital competition amid a global interest rate reset is reshaping fixed income markets, where expanding government borrowing and heavy artificial intelligence investments elevate financing costs and expose borrowers with deteriorating balance sheets to sharper market scrutiny. Given the fluid backdrop and elevated policy uncertainty, Stopford confirmed that his investment team has opted for the time being to avoid virtually all non-core sovereign debt across Europe.